Newsletter Subscribe
Enter your email address below and subscribe to our newsletter
Enter your email address below and subscribe to our newsletter
 ByJohn A
Finding the right property in Chicago requires more than browsing photos and comparing asking prices. Buyers need to consider property types, neighborhood characteristics, taxes, financing, and long-term ownership costs before deciding which home suits their needs. A structured search can help you identify suitable properties and make informed decisions throughout the buying process.
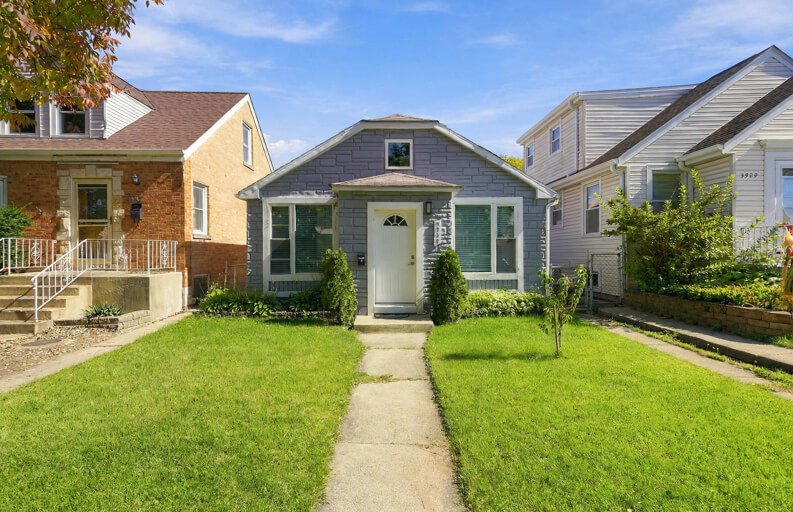
Exploring chicago real estate listings is a useful starting point for comparing available homes and narrowing your options. Chicago offers a diverse housing market, including single-family houses, condominiums, townhouses, multi-unit properties, and new construction. Prices, property features, and ownership costs can vary considerably depending on the location and type of home.
This guide explains how to search listings effectively, evaluate properties beyond their asking prices, research neighborhoods, and prepare for a home purchase.
Chicago’s housing market includes properties with different price points, architectural styles, and ownership requirements. Understanding local market conditions helps buyers set realistic expectations and assess whether a property represents suitable value.
Listing inventory refers to the homes currently available for sale. When inventory is limited relative to buyer demand, competition for desirable properties may increase. When more homes are available, buyers may have additional opportunities to compare options and negotiate.
Market conditions can vary by neighborhood, property type, and price range. A citywide trend does not necessarily reflect conditions for a particular condominium or single-family home. Review current listings, recent sales, and how long comparable properties have remained on the market before making decisions.
Property prices can differ according to neighborhood, square footage, building condition, property age, and nearby amenities. Parking availability, outdoor space, building facilities, and access to transportation may also affect value.
Compare homes with similar characteristics in the same general area whenever possible. This helps you understand whether differences in asking prices reflect meaningful variations in size, condition, location, or included features.
Real estate listings and market conditions change regularly. Older asking prices or sales data may not accurately represent the options currently available.
Check listing dates, price adjustments, property status, and recent comparable sales. Before making an offer, verify availability and review the latest information with an appropriate real estate professional.
Your preferred property type will influence your budget, maintenance responsibilities, financing requirements, and future flexibility. Understanding the main options can help you focus your search.
Single-family homes generally provide a separate living structure, often with private outdoor space and a greater degree of control over the property. Buyers should consider exterior maintenance, repairs, parking, and utility costs.
Multi-unit properties contain more than one residential unit and may appeal to buyers evaluating rental income opportunities. However, rental properties require additional research into local regulations, building condition, operating expenses, and applicable financing requirements. Potential income should never be assumed without reviewing the property’s circumstances.
Condominiums can offer access to shared building amenities and may involve less direct exterior maintenance. Buyers should examine association fees, financial reserves, building rules, insurance responsibilities, and any planned assessments.
Townhouses can provide multiple levels and a different balance of space and privacy. Ownership and maintenance responsibilities vary by development, so review the governing documents before purchasing.
New construction may offer modern layouts, updated systems, and opportunities to select certain finishes. Buyers should confirm the completion timeline, included features, builder warranty, and additional costs.
Existing homes may provide established surroundings, mature landscaping, or distinctive architectural features. Their condition and maintenance needs can vary, making property inspections and careful disclosure reviews important.
A clear search strategy helps you avoid spending time on properties that do not meet your essential requirements. Establish your priorities before comparing individual listings.
Determine your comfortable purchase price by considering your savings, expected mortgage payment, income, and other financial obligations. Include property taxes, insurance, closing costs, maintenance, and association fees where applicable.
Separate essential requirements from preferences. Your essential criteria might include a minimum number of bedrooms or a particular commute, while preferred features could include a balcony, additional storage, or a specific architectural style.
Use listing filters to narrow properties according to price, bedrooms, bathrooms, property type, square footage, parking, and other relevant features.
Check the listing details carefully because similar properties may differ in important ways. Review floor plans, photographs, property descriptions, and information about shared facilities. Verify measurements and included features when they affect your decision.
Saved searches and listing alerts can help you monitor newly listed homes, price reductions, and changes in availability. Set alerts around your preferred price range and property criteria to keep your search manageable.
Review alerts regularly, but verify each property’s current status before arranging a viewing or preparing an offer.
Two properties with similar asking prices can have very different ownership costs. Evaluating the full financial picture can help you choose a home that remains affordable after closing.
Property taxes are an important part of homeownership expenses in Chicago. Review available tax records and understand that assessments and future tax bills may change. Consider insurance premiums, utility costs, and any condominium or homeowners association fees.
For condominiums, investigate whether the association has adequate reserves and whether special assessments or planned repairs could affect owners. Include these expenses when estimating your total monthly housing cost.
Recent comparable sales can provide useful context for assessing an asking price. Look for properties with similar locations, sizes, conditions, and features.
Active listings show what sellers are currently asking, while completed sales provide evidence of prices buyers have agreed to pay. Neither guarantees the value of a particular home, so consider differences in property condition and market timing.
Review available seller disclosures and ask questions about known issues, renovations, and the condition of major systems. Pay attention to roofing, plumbing, electrical systems, heating and cooling equipment, and signs of water intrusion.
An independent professional inspection can help identify potential problems that may not be obvious during a viewing. Use the findings to understand likely repair costs and determine whether further specialist evaluations are necessary.
A property should suit your daily routine as well as your financial plans. Research the surrounding area to understand transportation, amenities, regulations, and other factors that could influence your experience as a homeowner.
Consider access to public transportation, major roads, walking routes, and cycling infrastructure. Estimate commute times at the hours you would normally travel because traffic and transit schedules can affect journey duration.
Check the distance to your regular destinations rather than relying only on general neighborhood descriptions.
Consider access to grocery stores, healthcare facilities, parks, restaurants, recreation, and other services you use regularly. Visit the surrounding area at different times when possible to assess traffic, noise, parking, and general activity.
Think about both current convenience and whether nearby development could change the area’s character.
If school access matters to your household, verify current attendance boundaries directly with the relevant school district. Boundaries and enrollment policies can change.
Also investigate zoning, permitted property uses, renovation requirements, and applicable local rules. For multi-unit properties or homes intended for rental use, confirm relevant requirements before purchasing.
Once you identify a suitable home, evaluate its price and purchase conditions before submitting an offer. Preparation can help you make decisions without overlooking important contractual details.
Use comparable sales, property condition, listing history, and current competition to assess an appropriate offer. The asking price is a starting point, not necessarily a definitive measure of market value.
Review the proposed price, earnest money, closing date, included items, and other terms. Your offer strategy should reflect your financial limits and the property’s characteristics.
Obtain mortgage preapproval where appropriate and understand the lender’s requirements. Budget for inspections, appraisal costs, closing expenses, and any necessary repairs.
Review financing, inspection, appraisal, and other applicable contingencies before signing. Their availability, wording, and deadlines depend on the contract and transaction. Understand your rights and obligations if a condition is not satisfied.
A licensed real estate agent can help interpret listing information, arrange viewings, evaluate comparable properties, and negotiate purchase terms. Buyers should understand the agent’s role and compensation arrangement before entering into an agreement.
During closing, review the final documents, financial figures, title information, and agreed conditions carefully. Seek qualified legal or financial advice when needed.
Reducing purchase costs involves looking beyond the asking price. Comparing expenses and understanding the terms of professional agreements can help buyers manage their budgets more effectively.
Closing costs may include lender fees, appraisal expenses, title-related charges, prepaid taxes, insurance, and other transaction costs. The exact amounts depend on the property, lender, and transaction.
Request a detailed estimate early and keep sufficient funds available for expenses beyond your down payment.
Before signing a buyer-agent agreement, review the services covered, agreement duration, termination provisions, and compensation terms. Understand how the agent will be paid and whether you could be responsible for any amount not covered by another party.
Ask questions about unclear provisions before agreeing to the arrangement.
Some real estate platforms may offer eligible buyers a commission rebate or other savings arrangement. Availability and eligibility depend on the platform’s policies, transaction details, applicable law, and agreement terms.
Review the conditions carefully and confirm how any rebate would be calculated, when it would be provided, and whether lender or transaction requirements apply. Do not assume every purchase qualifies or that a rebate will cover all buying expenses.
You can search online real estate platforms, brokerage websites, and property listing services. Compare filters, listing details, and property status, and verify availability before arranging a viewing.
Listings can change whenever a property is added, repriced, reserved, sold, or removed from the market. Check listing updates regularly and confirm current status with the listing contact.
Compare location, square footage, condition, property taxes, insurance, association fees, and likely repair expenses. Recent comparable sales and professional inspections can help you evaluate differences beyond the asking price.
An independent inspection can identify visible defects and areas requiring further evaluation. Review the inspection contingency and contract deadlines, and arrange any necessary specialist assessments.
Some platforms offer rebates to eligible buyers, but terms and availability vary. Review the written conditions and confirm applicable transaction, lender, and legal requirements before relying on potential savings.
Finding the right property involves balancing location, affordability, condition, and long-term ownership costs. A structured search helps you compare homes based on your priorities rather than relying solely on listing photographs or asking prices.
Start by setting a realistic budget, identifying preferred property types, and researching neighborhoods that suit your needs. Review comparable sales, verify listing details, and understand your contractual obligations before making an offer.
You can explore property options through IvyGro and use your preferred criteria to narrow your search. If you need further information about the platform, visit the contact page. Careful research and a clear understanding of the buying process can help you choose a Chicago property that aligns with your financial goals and housing requirements.